A Brief History of Gamestonk
January 28, 2021
Before the rocket ships and tendies, here’s how GameStop transformed into Gamestonk.
WallStreetBets and the hero of the story
Reddit is an online network of communities known as subreddits. r/WallStreetBets is a large subreddit where members generally share high-risk investment, trading ideas, and memes. According to founder Jaime Rogozinski, it’s “an alternative to the conservative, index-investing mindset that prevailed at the time. There’s a place in the market for diversified, low-risk investments. This isn’t it.“ In 2020, r/WallStreetBets surpassed one million members. They even had their own championship series planned. I joined several days ago at 2.4m members, today it’s 4.3m and counting.
Recently I tweeted about Twitter being the free tier to the world’s best thinking. Well, the same goes for Reddit, YoutTube, TikTok, etc. That’s right, you can find brilliant financial research hidden in r/WallStreetBets. Epsilon Theory describes it best as an off-off Wall Street source of investment information.
The mythical figure at the center of r/WallStreetBets and GameStop is a user called u/DeepF**kingValue. You can go back through his posts as far as September 2019. At that point he had roughly $50k invested in call options of GameStop stock (call options = a contract to buy a security in the future at a specified price and date).
This reddit user posted an hour long YouTube video describing his investment thesis for being long GameStop (long = expecting the stock to go up). He presented objective research of both objective and subjective data. For example, he walks through the process of theorizing what will happen to physical game discs based on disparate materials. He also turns to GameStop’s financial statements to analyze free cash flows, working capital management, and monetizable assets. For those claiming GameStop was done because malls were closed, he presented a fundamental and technical analysis that argued otherwise.
Since then he has posted weekly updates of his GameStop position, which as of yesterday was worth over $47m. According to various redditors, they’ve never been so happy to see someone else making money. These were very likely the same users proclaiming his position to be terrible for most of the past 18 months. Like Nassim Taleb writes in The Black Swan, “The problem of lumpy payoffs is not so much in the lack of income they entail, but the pecking order, the loss of dignity, the subtle humiliations near the watercooler….. The person involved in such gambles is paid in a currency other than material success: hope.”
Then the narrative shifted from GameStop to $GME. GameStop is the brick and mortar business that deals in video games. $GME is an entirely separate entity.
Shooting for the moon
I do not believe there’s a single reason for $GME increasing from a $3b market cap to $24b in the past two weeks. As compelling as our hero’s case was, nothing fundamentally supports this valuation.
[caption id=“” align=“alignnone” width=“803”]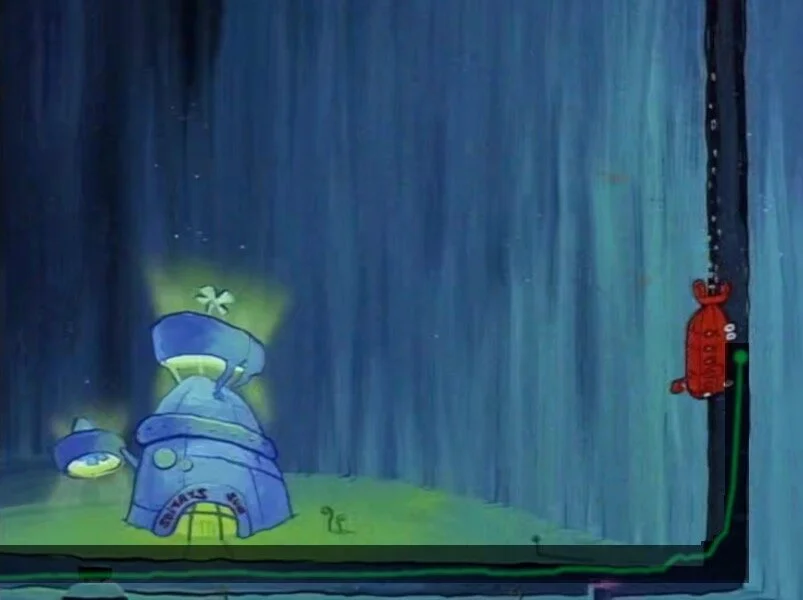 $GME. I knew this looked familiar….. [/caption]
Consider this confluence of events:
1. “Robinhood” spiked as a Google search term throughout 2020 compared to 2016-2019. In the past 12 months, the peaks were the beginning of the pandemic and this entire month.
2. Prominent investors took a long position in $GME. Michael Burry, head of Scion Asset Management and major character in The Big Short, made a substantial investment in GameStop in April 2019 based on his fundamental analysis. Ryan Cohen, former CEO and co-founder of Chewy, also invested and now has three seats on the board.
3. $GME became the beneficiary of cumulative advantage. People are buying GameStop because people are buying GameStop. There’s a NYT article from 2007 titled Is Justin Timberlake a Product of Cumulative Advantage? One paragraph reads:
“When people tend to like what other people like, differences in popularity are subject to what is called ‘cumulative advantage,’ or the ‘rich get richer’ effect. This means that if one object happens to be slightly more popular than another at just the right point, it will tend to become more popular still. As a result, even tiny, random fluctuations can blow up, generating potentially enormous long-run differences among even indistinguishable competitors – a phenomenon that is similar in some ways to the famous ‘butterfly effect’ from chaos theory.”
Gamestonk!! https://t.co/RZtkDzAewJ
— Elon Musk (@elonmusk) January 26, 2021
4. The opportunity for a short squeeze. For those unfamiliar with the term, Sahil Bloom has an excellent thread on twitter explaining this and several other concepts. Basically, enough people were short GameStop (short = expecting the stock to go down) that they were not all able to buy shares to close out their short positions at once. That is why you’ll hear people mentioning short-interest ratio. As Nassim Taleb says “The market is like a large movie theater with a small door. And the best way to detect a sucker is to see if his focus is on the size of the theater rather than that of the door.” With the amount of trading platforms crashing, retail investors are recognizing this lesson.
Short Squeeze 101
If you follow financial markets (or if you watch Billions), you’ve heard the phrase “short squeeze” used quite frequently.
But what is a “short squeeze” and how does it work?
Here’s Short Squeeze 101!
👇👇👇
— Sahil Bloom (@SahilBloom) August 5, 2020
5. The power of memes and celebrities. Much like Matt Levine’s boredom market hypothesis, I have my theory of memes and celebrities as the modern equivalent of bread and circuses. Against my best efforts, my Twitter timeline is still permeated by Bernie Sanders memes and news that Halsey is now pregnant. Just a few weeks ago it was Baby Yoda and Kim Kardashian. The cycle never ends, and r/WallStreetBets is being referred to as the “meme stock market.” A growing number of redditors are reminding institutional investors that, as Keynes said, “the market can stay irrational longer than you can stay solvent.”
The way we speak now may ensure nothing transcendent can ever happen again:
“Bruh, Leonardo was da GOAT among cross platform creators. If he’d crowdfunded or pivoted to a freemium model coupled to a revenue share, meme distribution could have scaled his content. lol! Self-own.” pic.twitter.com/LV1wLz5iJJ
— Eric Weinstein (@EricRWeinstein) January 9, 2021
6. Low opportunity costs for capital. Two people I’ve learned a lot from are Howard Marks and Bill Gurley. This podcast interview from Jan. 4 featured both of them, and they talked through several macro issues. Currently, there is a low opportunity cost for capital. Opportunity cost refers to the best option you forgo for any decision. For example, the opportunity cost of reading at night could be a few extra minutes of sleep. Due partially to the sustained low interest rate environment we’re in, there are few appealing alternatives to having money in equities.
What do we do now?
If you haven’t seen it yet, stop what you’re doing and listen to Chamath Palihapitiya’s interview on CNBC yesterday. Chamath delivers the equivalent of a rousing halftime speech that got me fired up for the future.
Hedge funds were guilty of “picking up pennies in front of a steamroller,” and some people are proposing that retail investors be punished (again). Instead of cementing disparity in the market, as Chamath explains, we need to be leveling the playing field.
If you still believe in efficient market hypothesis you do NOT have to worry about Biden’s tax plan
— Dr. Parik Patel, BA, CFA, ACCA Esq. 💸 (@ParikPatelCFA) January 26, 2021
Further reading:
Matt Levine’s newsletter - Money Stuff
Planet Money: The Tale of the Onion King